Bitcoin ETF Outflows Explained: What Fund Flows Can—and Cannot—Tell You

Bitcoin ETF outflows can reveal changes in demand for exchange-traded exposure, but they do not explain the entire Bitcoin market. Before treating an outflow headline as a directional signal, readers need to distinguish net redemptions, trading volume, changes in assets under management and the movement in Bitcoin’s price.
This analysis explains how to read Bitcoin ETF flow data, build a consistent comparison and recognise when a popular interpretation goes beyond the evidence. It uses hypothetical calculations instead of presenting an unverified live flow total.
Analysis date: 15 November 2026. This is a methodology-led Market Insights article. It does not assert a current daily outflow figure, identify the motives of individual holders or provide a price target.
Table of Contents
- First identify which product the headline means
- Outflow is not the same as trading volume
- Why falling assets under management can mislead
- Read the methodology before comparing providers
- Put the figure in proportion
- What outflows cannot reveal about investor motives
- How to connect flows with Bitcoin market structure
- Three interpretations to test, rather than assume
- A repeatable five-minute review
- Frequently asked questions
First identify which product the headline means
“Bitcoin ETF” is common shorthand, but product structures differ. The SEC’s investor bulletin distinguishes spot products holding crypto assets from products using futures, and notes that US spot Bitcoin trusts are not investment companies registered under the Investment Company Act of 1940.
For a practical example of issuer reporting, the iShares Bitcoin Trust product page publishes fields including net assets, net asset value, shares outstanding and trading volume. Those fields describe different things and carry their own observation dates.
The first research step is to record the exact product, market, structure and reporting period. Combining a spot product’s data with a futures product’s data without explanation can produce a misleading total.
Outflow is not the same as trading volume
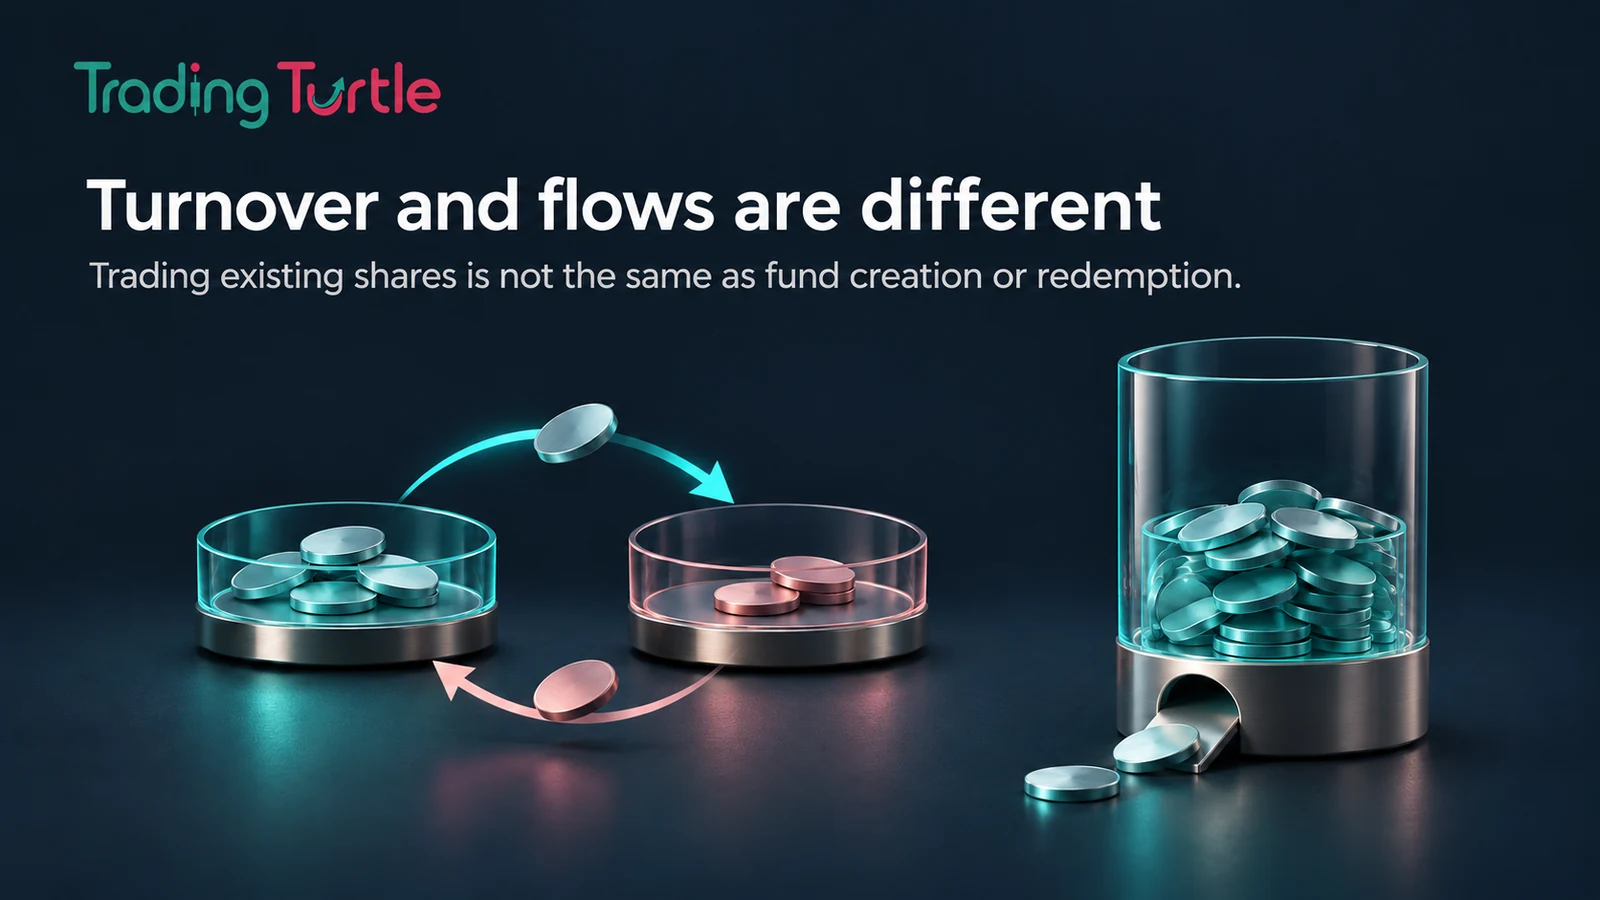
Trading volume measures shares changing hands on an exchange. A buyer can purchase existing shares from a seller without the fund itself receiving new net investment. High volume therefore does not establish a large inflow.
Net flow aims to capture investment entering or leaving the product through the relevant creation and redemption process. The precise calculation should follow the issuer’s structure and the data provider’s stated methodology.
Imagine 10 million existing shares change hands in a day while the outstanding share count remains unchanged. There has been substantial trading, but that fact alone does not establish net creation or redemption. Using turnover as a substitute for flows would overstate what the data shows.
Conversely, a change in outstanding shares can be informative even if a reader has focused mainly on the day’s exchange volume. The two measures complement each other when their definitions are kept separate.
Why falling assets under management can mislead
Assets under management change when the value of the underlying holdings changes, when investment enters or leaves, and potentially through other product-specific effects. A lower dollar total is not automatically a withdrawal of the same amount.
Consider a simplified fund holding 1,000 Bitcoin. At a hypothetical Bitcoin price of $70,000, that holding is worth $70 million. If the price falls to $63,000 while the quantity remains 1,000, the value becomes $63 million. The $7 million decline is a valuation effect in this example, not evidence of $7 million of redemptions.
Now suppose the quantity also changes. The analysis must separate the holding change from the price change and account for fees or other relevant adjustments. Subtracting two end-of-day dollar totals without those checks can mix several effects into one alarming headline.
This example does not represent any named fund’s current holdings. It demonstrates the arithmetic behind a common interpretation error and shows why quantities, prices and dates should be recorded together.
Read the methodology before comparing providers
Flow dashboards can differ in coverage, cut-off time and revision practices. A figure marked preliminary should not be presented as final. A total for selected products should not be described as the entire market.
Start by listing the included products. Note whether the dataset covers spot products, futures products or a combination. Record the reporting timezone and the date assigned to each session. Then check whether the provider explains how it estimates creations and redemptions.
When two sources disagree, do not automatically choose the larger number. Look for an omitted product, a late update, a currency conversion or a different reporting cut-off. If the difference cannot be resolved, retain both definitions and state the limitation.
A useful research note should let another reader reproduce the comparison. That is more valuable than quoting a precise number without the steps that produced it.
Put the figure in proportion
An absolute dollar amount means more when compared with the size of the relevant product or group. A hypothetical $100 million outflow is 1% of a $10 billion base but 10% of a $1 billion base. The same headline number describes very different magnitudes.
The denominator must match the numerator. Comparing a one-product outflow with total assets across an unrelated group can make the percentage appear smaller than the exposure being discussed. Comparing different dates can introduce a second distortion.
It can also help to examine several sessions rather than one isolated print. A rolling total provides context, but the chosen window should be disclosed. Selecting the only window that supports a preferred narrative is not a sound analytical method.
For practical notes, write the amount, covered products, session date, denominator date and source on the same line. This small habit prevents many errors when revisiting research later.
What outflows cannot reveal about investor motives
An outflow does not identify the ultimate investor’s complete portfolio. A holder could be reducing exposure, rebalancing, switching products or adjusting a hedged position. The flow alone cannot choose among those explanations.
This is particularly important when a headline assigns a single motive to “institutions.” A product can be held through several types of accounts and intermediaries. Public product totals do not automatically disclose who made each decision or why.
The appropriate language is conditional: the data is consistent with reduced demand for that product over the measured period. Stronger statements require additional evidence. Avoid turning a plausible interpretation into a reported fact.
An analyst should also resist the opposite mistake. Uncertain motives do not make the flow meaningless. They simply limit what can responsibly be inferred from it.
How to connect flows with Bitcoin market structure
Flows can be compared with price, liquidity and positioning, but the timestamps must align. A US trading session does not cover every hour of the continuously traded crypto market. A weekend price move should not be assigned to a same-day US fund flow that does not exist.
Study whether price is holding, extending or reversing around the period of observed demand. Then ask what other information arrived: macroeconomic developments, market-specific events or changes in trading conditions. Correlation over a short period does not establish a single cause.
If derivatives data is included, define the measure and venue coverage. Open interest, funding and liquidation figures are not interchangeable. A chart that combines them without explanation can give a false sense of confirmation.
Readers learning those concepts can start with Trading Turtle’s Crypto Basics and Technical Analysis resources. Understanding the measurement comes before interpreting the signal.
Three interpretations to test, rather than assume
One interpretation is persistent withdrawal of demand from the measured products. Evidence would include a sustained pattern across comparable sessions and relevant products. Even then, the broader market response needs separate examination.
A second interpretation is product rotation. Some products may lose assets while others gain. Aggregate data and product-level data would then tell different but compatible stories. The analysis should show both rather than selecting whichever is more dramatic.
A third interpretation is a temporary adjustment. An isolated outflow followed by mixed or reversed flows may warrant a different conclusion from a continuing series. The evidence needs time to develop; a single day cannot establish persistence.
No probability is assigned to these scenarios. Their purpose is to make a research process explicit and create clear conditions under which an interpretation should change.
A repeatable five-minute review
Identify the product universe and source. Confirm whether the latest figure is final. Check the dates on net assets and shares outstanding. Read the provider’s calculation notes if deriving a flow estimate.
Compare the result with the same products over a disclosed multi-session window. Separate changes in holdings from changes in their dollar value. Record any unresolved discrepancy instead of quietly correcting it in favour of a preferred story.
Then write one sentence describing the observation and another describing the interpretation. For example: “The measured products recorded net redemptions during the stated sessions” is an observation. “This may reflect reduced appetite for exposure” is an interpretation requiring context.
Finally, keep the trading decision separate. A data point does not establish position size or acceptable loss. Use a Trading Journal to record the thesis and a Pre-Trade Checklist to evaluate any proposed execution.
Frequently asked questions
Are Bitcoin ETF outflows the same as Bitcoin selling volume?
No. Product flows, exchange trading volume and underlying market activity measure different processes. They should be connected only with a clear explanation of the product and methodology.
Can assets under management fall without redemptions?
Yes. A fall in the value of the underlying asset can reduce the dollar value of holdings even when the quantity held has not changed. Fees and other product-specific effects may also matter.
Do outflows prove that institutions are bearish?
No. Aggregate product data does not reveal each holder’s motives or complete portfolio. Persistent outflows can still be relevant evidence, but the interpretation must stay within those limits.
Should one day’s flow determine a trading decision?
A single observation is insufficient to establish a complete trading plan. Check the data’s scope, wider context, risk and the evidence that would invalidate the interpretation.
Sources and method: SEC investor bulletin on Bitcoin and Ether ETPs and iShares issuer product information, reviewed 15 November 2026. No current live flow total is asserted. Calculations and research examples are original illustrations. This article provides education and analysis, not a recommendation to invest in any product.