Paytm PPI Approval Analysis: From Regulatory Milestone to Business Results

Paytm’s preliminary PPI authorisation creates a business question rather than an automatic earnings conclusion. The useful task for readers is to trace the path from regulatory permission to a functioning product, repeat customer use and measurable financial contribution.
This Paytm PPI approval analysis sets out that path. It separates the event confirmed by the company from the assumptions needed to value a possible wallet business, and identifies the disclosures that would make the next stage easier to assess.
Analysis date: 15 November 2026. This article evaluates a regulatory milestone. It does not provide a target price, assume a launch date or forecast undisclosed revenue. All numerical business examples are hypothetical.
Table of Contents
- What has actually changed?
- Identify the entity before interpreting the brand
- The milestones between permission and profit
- Why transaction volume is not the same as revenue
- A useful unit-economics worksheet
- Where the opportunity could come from
- Three scenarios worth monitoring
- What would weaken an optimistic interpretation?
- How to follow the next disclosures
- Frequently asked questions
What has actually changed?
One 97 Communications’ 13 November filing says its subsidiary PPSL received in-principle RBI authorisation for prepaid payment instruments. It explicitly links offering instruments such as a wallet to the grant of final authorisation. Our news report explains the announcement.
For analysis, that wording establishes the starting point. It does not establish a completed rollout, a customer base for the proposed product or a contribution to earnings. Those are further milestones requiring further evidence.
Markets can react to a change in expectations before financial statements change. That is normal, but it creates a common analytical mistake: treating an increase in perceived opportunity as if the opportunity had already been converted into cash.
Identify the entity before interpreting the brand
A familiar consumer brand can cover several services and legal arrangements. The named entity in a filing matters because authorisations, contracts, obligations and reported results attach to specific businesses.
Here the document names Paytm Payments Services Limited. An analyst should retain that name in their notes instead of replacing it with a broad statement that every Paytm service has received a new permission.
This discipline prevents several errors. It avoids confusing a payment instrument with a banking product. It also keeps a later announcement about a different subsidiary from being treated as automatic evidence that this particular approval process has advanced.
When a corporate structure is complex, a simple worksheet helps: list the parent, the subsidiary named in the document, the permitted activity and the reporting segment where any eventual impact might appear. Leave unverified links blank.
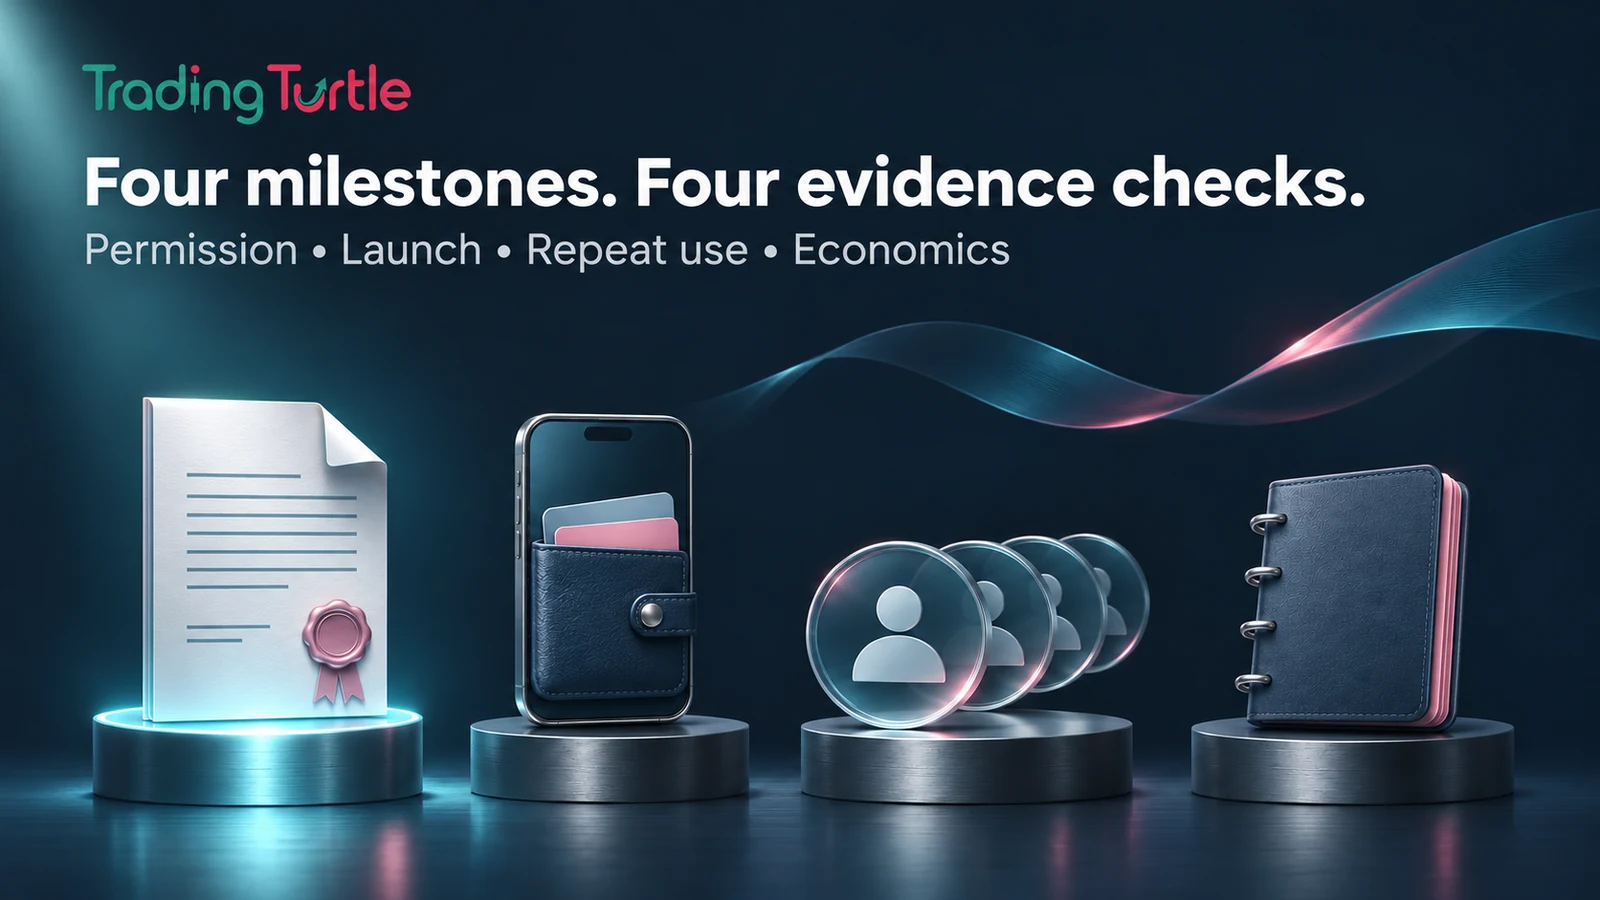
The milestones between permission and profit
The first stage is regulatory completion. The evidence would be the relevant final authorisation and any conditions explained in official communication. A headline about an application or preliminary decision cannot substitute for that document.
The second stage is operational readiness. The business needs a working product, appropriate processes and customer support. Readers should examine the actual offering and terms rather than assuming that a familiar interface makes implementation trivial.
The third stage is adoption. Downloads, registered users and active paying users are different measures. A product can attract attention without developing frequent use. Useful reporting would define activity and show whether it persists across comparable periods.
The fourth stage is economics. Transaction volume can grow while revenue or contribution remains weak. The business impact depends on how value is earned and what it costs to deliver the service.
Why transaction volume is not the same as revenue
Payment value measures money moving through a service. Revenue measures the amount the company recognises for the relevant activity. The two should not be used interchangeably.
For a purely hypothetical example, a service processing ₹100 crore with an effective revenue yield of 0.10% would generate ₹10 lakh before considering the nature of that yield and related costs. Doubling processed value would not necessarily double profit if incentives, processing expense or support costs also changed.
The example is intentionally simple. It is not an estimate for Paytm and does not imply that every wallet transaction earns a fee. Its purpose is to make the analytical bridge visible: activity needs a monetisation mechanism before it becomes revenue.
The next bridge is from revenue to contribution. A company may earn income from an activity while spending more to acquire or serve the users involved. That is why the definition of each metric matters as much as the headline growth rate.
A useful unit-economics worksheet
Begin with a clearly defined active user base and the period measured. Add transactions per active user, average transaction value where relevant and the revenue mechanism actually disclosed. Avoid inventing a take rate to fill a missing number.
Then separate costs that vary with activity from broader operating costs. Customer incentives, processing and service costs may behave differently from development or compliance expenditure. The classification should follow company reporting rather than an analyst’s preferred narrative.
Finally, compare cohorts over time if that information is available. A group of customers acquired through a promotion may behave differently after the promotion ends. Sustained use with lower support and acquisition expense would be more informative than a single strong launch month.
If the necessary data is absent, the correct result is an incomplete model with explicit questions. A precise-looking spreadsheet built on unverified assumptions can be less useful than a short list of missing evidence.
Where the opportunity could come from
A successful payment product must solve a customer problem. Possible sources of value include a convenient payment experience, useful merchant acceptance and a service that customers choose repeatedly. These are areas to investigate, not claims about features that have already launched.
For the business, distribution can matter because an existing relationship may reduce the effort required to introduce another service. But a large audience is not the same as product demand. Users still compare convenience, trust, cost and alternatives.
An analyst should ask whether the proposed service adds a distinct reason to remain active or merely duplicates something the customer already has. This question connects product design to retention and prevents brand scale from being treated as an automatic competitive advantage.
The RBI’s PPI framework provides the regulatory context. The commercial assessment still requires evidence about the eventual offering and its actual performance.
Three scenarios worth monitoring
In a strong execution scenario, the authorisation process advances, the product becomes available on clear terms and repeat usage develops without disproportionate expense. Supporting evidence would come from official milestones and consistently defined operating metrics.
In a slower adoption scenario, the product launches but customers use it selectively or incentives remain necessary. The key question would be whether the company adjusts its design and spending while preserving useful customer relationships.
In a delay scenario, the next regulatory or operational milestone takes longer than expected. Readers should examine the company’s explanation and distinguish a timing change from a fundamental change in the opportunity. None of these scenarios is assigned a probability here.
The value of scenario analysis is that it makes future evidence actionable. A reader can update their interpretation when facts change instead of defending a fixed opinion formed on announcement day.

What would weaken an optimistic interpretation?
Persistent delays without a clear explanation would deserve attention. So would growth figures that change definition between periods, strong transaction headlines without a revenue bridge or customer incentives that expand faster than repeat engagement.
These are general analytical warning signs, not allegations about the company. Their role is to establish what information would challenge the thesis before enthusiasm makes that challenge uncomfortable.
The same standard applies in the opposite direction. Better-than-expected adoption or a clearly reported improvement in economics should be acknowledged rather than dismissed because it conflicts with an earlier cautious view.
Good analysis is revisable. Writing down the evidence that would change your mind is often more valuable than producing a confident conclusion from incomplete information.
How to follow the next disclosures
Read the original exchange filing before commentary. Record the date, named entity and exact stage reached. Compare the new document with the previous one, looking for changes in permission, conditions or commercial availability.
At results time, check whether management reports product-specific figures or discusses the activity within a broader segment. Do not calculate a narrow product margin from an unrelated group-wide number. If management does not isolate the contribution, say so.
A useful follow-up note should also distinguish a management objective from a completed milestone. Record who made the statement, the date and any conditions attached to it. If a target changes, compare the explanation with the earlier statement rather than treating the new date as independent progress. This creates a fair record of delivery without assuming that every delay means failure or that every positive statement has already become a business result.
Keep market-price observations separate from operational evidence. A rising share price is evidence of trading demand at that time; it does not prove a forecast is correct. Equally, a falling price does not establish that a product has failed.
Readers can use Trading Turtle’s Stock Market Basics to strengthen their understanding of listed-company information, and the Trading Journal to record assumptions and review them against later evidence.
Frequently asked questions
Is Paytm’s in-principle PPI authorisation the same as a launched wallet?
No. The company’s disclosure distinguishes preliminary authorisation from the final authorisation needed to offer the instruments. Product availability needs its own confirmation.
Does the approval establish higher future profit?
No. Profit would depend on the eventual offering, customer use, monetisation and costs. The announcement changes the opportunity set without proving the financial outcome.
Which metrics matter after a launch?
Look for consistently defined active usage, repeat transactions, disclosed revenue mechanisms and the costs of acquiring and serving customers. Read the definitions before comparing figures.
Why does the subsidiary name matter?
The permission applies to the entity and activity named in the document. Using the broader brand alone can lead readers to infer changes to unrelated products or businesses.
Sources and method: One 97 Communications’ 13 November 2026 filing, RBI PPI FAQ and Master Directions, reviewed 15 November 2026. Milestones, business examples and scenarios are Trading Turtle’s analytical framework. Educational information only; no investment recommendation or target price is provided.